MSC tightens grip on Asia-South America trade as Hapag-Lloyd exits
Subscribe to our free newsletter today to keep up to date with the latest renewable energy news.
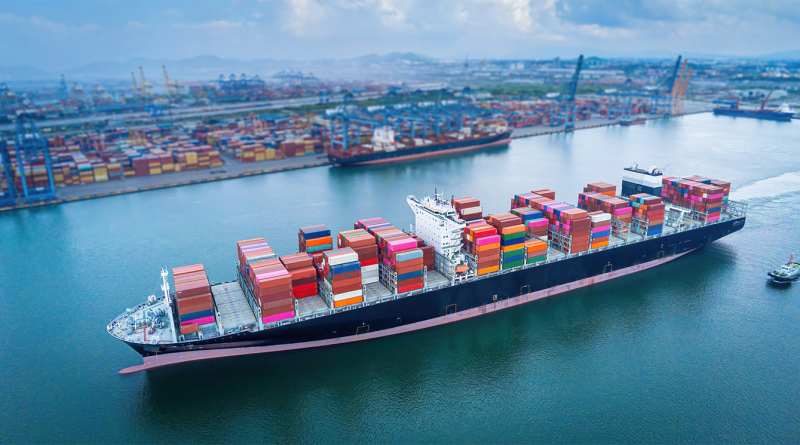
Hapag-Lloyd’s decision to withdraw from the MSC-led Ipanema service connecting Asia with the east coast of South America marks another significant development in the restructuring of container shipping networks, as carriers reconsider vessel-sharing agreements, operational independence and commercial partnerships across major international trade routes.
The German shipping company will leave its existing vessel-sharing agreement with Mediterranean Shipping Company (MSC) and Ocean Network Express (ONE) in 2027, ending a three-carrier arrangement that has provided weekly container services between Asian manufacturing centers and major South American ports.
MSC and ONE will continue operating Ipanema under a revised agreement, with the first sailing scheduled to depart Shanghai on April 3, 2027. MSC intends to introduce additional vessels to compensate for Hapag-Lloyd’s withdrawal, maintaining the service’s existing geographical coverage and weekly frequency.
The announcement comes amid a broader reorganization of container shipping services between Asia and South America, where competing alliances and independent carriers are adjusting their networks in response to changing commercial priorities.
For cargo owners, freight forwarders and logistics providers, these developments extend beyond changes in carrier partnerships. The restructuring could influence vessel availability, shipping schedules and access to alternative services, particularly as several major operators revise their South American networks within a relatively short period.
MSC and ONE retain Ipanema as Hapag-Lloyd reviews its fleet options
The Ipanema service currently operates with 13 vessels averaging approximately 11,700 twenty-foot equivalent units (TEUs), according to figures from Xeneta’s eeSea liner database reported by The Loadstar. Hapag-Lloyd contributes five vessels to the existing arrangement, representing a substantial share of the ships deployed on the route.
MSC plans to introduce additional tonnage when the revised vessel-sharing agreement takes effect, allowing the carrier and ONE to maintain Ipanema’s established network without Hapag-Lloyd’s participation.
The service will retain its existing Asian connections through Shanghai, Ningbo, Shekou, Hong Kong and Singapore, followed by calls at South American ports including Santos, Paranaguá, Navegantes, Montevideo, Buenos Aires and Rio Grande.
Preserving these port calls should limit the immediate disruption associated with Hapag-Lloyd’s departure, although the operational consequences will depend on how replacement vessels are introduced and whether the revised network maintains its existing schedule performance.
An equally important question concerns the future deployment of Hapag-Lloyd’s five vessels.
Their withdrawal from Ipanema would release capacity that could potentially support the carrier’s other operations, including its recently introduced Asia-South America service developed with Israeli shipping company ZIM.
Hapag-Lloyd launched its AS3 service in September 2026, establishing a weekly connection between major Chinese gateways and Brazil in cooperation with ZIM. The service provides direct access to ports including Rio Grande, Paranaguá, Itajaí, Santos and Rio de Janeiro, with onward connectivity to River Plate destinations.
Additional vessel availability could give Hapag-Lloyd greater flexibility to strengthen that service or support other commercial arrangements, although the company has not publicly confirmed how its departing Ipanema vessels will be redeployed.
Another possibility involves Maersk’s ASAS service, where Hapag-Lloyd already participates through purchased vessel slots. Deploying ships into that network could deepen operational cooperation between the two carriers, which already work together under the Gemini Cooperation partnership.
Neither scenario has been confirmed, and the eventual deployment decision will depend on vessel requirements, commercial agreements and the changing capacity needs of the Asia-South America trade.
A broader alliance reshuffle is changing Asia-South America capacity
Hapag-Lloyd’s departure follows several developments that are restructuring the competitive environment for container shipping between Asia and the east coast of South America.
Maersk and CMA CGM announced the termination of their joint ASAS2/SEAS3 service, with the final sailing under the existing arrangement scheduled to depart Shanghai on Dec. 8, 2026.
Maersk will continue serving the region through its independently operated ASAS service, reflecting a preference for greater operational control over vessel deployment, service schedules and network development.
CMA CGM is reorganizing its presence around services operated with Ocean Alliance partners, creating a more concentrated network structure involving established alliance members.
These changes demonstrate how shipping companies are reassessing partnerships on routes that have traditionally involved cooperation between carriers belonging to different global alliances.
Such agreements allow operators to share the financial burden of vessel deployment, improve service frequency and offer broader geographical coverage without independently committing ships to every route. Their commercial benefits can diminish when carriers pursue different network strategies or seek greater control over capacity.
Industry analyst Nils Roche, writing in The Loadstar, estimated that the wider restructuring could reduce nominal weekly capacity from Asia to the east coast of South America by approximately 4%.
The estimate reflects proposed changes in vessel deployment across several services rather than a confirmed reduction in available shipping space. Actual capacity will depend on replacement tonnage, revised rotations and any additional commercial agreements announced before the network changes take effect.
The implications are particularly significant for carriers with multiple overlapping partnerships. Hapag-Lloyd has positioned itself across several operational arrangements, maintaining its relationship with Maersk through Gemini Cooperation, developing services with ZIM and preparing to leave its existing agreement with MSC and ONE.
Its relationship with ZIM has attracted further attention following the announcement of a proposed acquisition in February 2026, although regulatory developments have complicated the transaction and its eventual outcome remains uncertain.
For MSC, the revised Ipanema arrangement offers an opportunity to increase its direct contribution to a commercially important service without changing the principal ports served. For ONE, continued participation preserves access to an established weekly route while sharing operational commitments with MSC.
The changes suggest that carrier partnerships are becoming increasingly selective, with shipping lines balancing the cost advantages of cooperation against the commercial benefits of controlling their own networks.
Shippers face new questions over capacity, reliability and port coverage
For importers, exporters and freight forwarders, the immediate concern is whether the evolving carrier arrangements will affect capacity availability, schedule reliability and direct connections between major trading centers.
The simultaneous restructuring of several Asia-South America services could create temporary complications for cargo planning, especially where shippers rely on particular carriers for access to specific ports.
Changes to vessel rotations can alter transit times, transshipment requirements and the frequency of direct services. Even where overall capacity remains relatively stable, the redistribution of ships between carriers can reduce the number of practical alternatives available for certain origin and destination combinations.
This distinction matters for businesses shipping time-sensitive goods or operating supply chains that depend on predictable delivery windows.
South America’s east coast is an important destination for Asian manufactured products, including machinery, consumer goods and industrial equipment, while container exports from the region include agricultural commodities and refrigerated cargo.
For these shipments, a service change that introduces additional transshipment or reduces weekly sailing options can have commercial implications extending beyond the ocean freight rate.
The forthcoming restructuring places greater importance on examining actual vessel rotations rather than relying exclusively on published carrier service coverage.
Freight forwarders may need to compare direct port calls, connections through regional hubs and available alternatives across different shipping networks. Cargo owners with concentrated carrier exposure could benefit from reviewing whether their existing contracts provide sufficient flexibility when schedules or operational arrangements change.
Network concentration presents another consideration. Carriers operating fewer services may achieve greater efficiency through consolidated vessel deployment, but shippers can face reduced flexibility when individual sailings are canceled or delayed.
The December 2026 changes involving Maersk and CMA CGM will provide an early indication of how effectively operators can manage the transition, followed by the revised MSC and ONE Ipanema arrangement in April 2027.
Much will depend on whether carriers can maintain service frequency while accommodating changes in vessel ownership, deployment and partnership structures.
For Hapag-Lloyd, the departure from Ipanema creates opportunities to concentrate capacity on services more closely aligned with its commercial relationships. MSC and ONE, meanwhile, will assume greater responsibility for an established route connecting two important trading regions.
The broader significance is the increasing willingness of container shipping companies to revise long-standing operational arrangements in pursuit of greater network control and commercial flexibility.
As these adjustments continue, the competitive position of carriers serving South America will depend not only on their available capacity but on the reliability, geographical coverage and flexibility of the services they provide.
For shippers planning cargo movements into 2027, understanding those differences may become more important than the alliance names attached to individual vessels.
Source:
The Loadstar