US weighs tariff relief for Canadian metals and autos
Subscribe to our free newsletter today to keep up to date with the latest renewable energy news.
A possible reduction in US tariffs on Canadian steel, aluminum and automobiles would provide manufacturers with some relief from one of the largest cost disruptions affecting North American industry, although it would not restore cross-border trade to the conditions that companies operated under before the latest tariff cycle.
The US is considering cutting tariffs on Canadian steel and aluminum from 50% to 25%, according to The Wall Street Journal, while automobile tariffs could fall from 25% to 15% under terms that remain under negotiation and may still change before any agreement is reached.
For companies purchasing metals, components or finished vehicles across the US-Canada border, reductions of that size would carry direct financial consequences because a 25% duty, though still substantial, changes sourcing economics considerably when compared with a 50% levy on the same product.
The scale of the trading relationship means those calculations extend far beyond individual steel mills, smelters or assembly plants, since US goods trade with Canada totaled an estimated $719.5 billion in 2025, including $336.5 billion in US exports and $383 billion in imports, according to the Office of the US Trade Representative.
Those figures reflect an industrial system built around decades of cross-border production, supplier specialization and regional sourcing rather than two neatly separated national markets, which means tariff relief could lower some of the cost of keeping that system operating while still leaving manufacturers exposed to trade barriers that were far less prominent only a few years ago.
Integrated factories make tariffs difficult to contain at the border
Steel and aluminum tariffs begin as border charges, but their impact can travel through several layers of production as importers, processors, component makers and manufacturers adjust prices to account for the higher cost of materials.
A manufacturer importing Canadian metal into the US may pay the tariff directly, while a supplier purchasing products made with imported material can encounter the same cost through higher prices, and automakers may face comparable exposure through components, assemblies and vehicles that cross national borders at different stages of production.
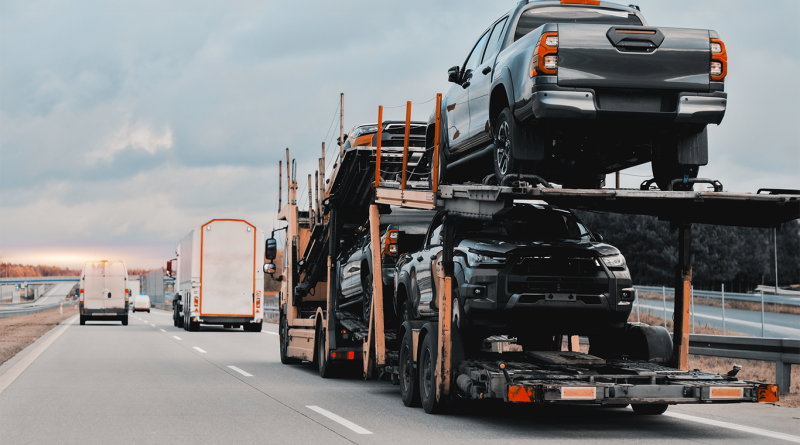
This structure makes tariff policy particularly consequential for the North American automotive industry, where production networks developed under decades of regional trade integration and where suppliers, assembly operations and logistics networks are distributed across the US, Canada and Mexico.
A vehicle’s commercial exposure can therefore depend on where parts originated, where manufacturing took place, how much qualifying regional content it contains and whether each stage of production satisfies the relevant trade rules.
Canada’s tariff measures illustrate the same complexity because the country maintains 25% tariffs on non-CUSMA-compliant vehicles imported from the US and on certain non-Canadian and non-Mexican content in compliant US vehicles, while countertariffs on US steel, aluminum and automobiles remain in force as negotiations continue.
The Canadian government has also created remission mechanisms for cases in which tariffed goods used as production inputs cannot reasonably be sourced domestically or from non-US suppliers, a policy response that reflects the difficulty of applying industrial tariffs without creating additional costs for domestic manufacturers that depend on imported materials or components.
For logistics teams, procurement executives and plant operators, lower tariff rates could influence inventory levels, supplier allocation, purchasing schedules, transport routes and working-capital requirements because companies that adjusted sourcing strategies around a 50% metals tariff may reach a different commercial decision when that rate falls to 25%.
A lower tariff would not automatically make the previous operating model economically attractive in every case, but it would create a new set of cost assumptions that companies would need to incorporate into sourcing and production planning.
A bilateral deal is part of a larger North American trade reset
The Canada negotiations are taking place as North American trade rules undergo a broader reassessment, with the first joint review of the US-Mexico-Canada Agreement bringing automobiles, steel, aluminum, rules of origin and economic security back into negotiations over how regional trade should operate.
US officials have placed particular attention on increasing manufacturing within North America and limiting the extent to which companies or inputs from outside the agreement can benefit from preferential access, which creates another layer of complexity for manufacturers assessing the value of potential tariff reductions.
A lower headline tariff can improve the cost of importing a product, but changes to rules of origin can alter which goods qualify for preferential treatment in the first place, while measures targeting third-country inputs could reshape supplier selection even when the tariff charged on qualifying Canadian goods declines.
For Canadian and US manufacturers, the policy direction points toward a North American trading system that remains highly integrated but places greater scrutiny on the origin of materials, components and investment, particularly in strategically sensitive industrial sectors.
That approach could favor companies with established regional production networks and higher levels of North American content, while creating more pressure for manufacturers that depend heavily on inputs from outside the region or operate in sectors where alternative suppliers are limited, more expensive or difficult to qualify.
The same policy shift may influence future capital investment because plants, supplier networks and distribution infrastructure can take years to build, leaving manufacturers unable to reorganize production every time tariff rates or trade rules change.
Executives therefore have to judge whether current trade measures represent short-term negotiating positions or a more durable change in how regional commerce will be managed, since that distinction can affect decisions involving new plants, supplier contracts, sourcing markets and long-term logistics infrastructure.
Manufacturers may gain relief without gaining certainty
A US-Canada agreement that lowers steel, aluminum and automobile tariffs would remove part of the immediate cost burden on cross-border industry, but manufacturers would still be operating under tariff rates that can materially affect margins, sourcing strategies and investment decisions.
Canada continues to seek relief from existing sectoral tariffs while retaining countermeasures on steel, aluminum and automobiles, and the wider CUSMA review leaves major questions around regional content, industrial policy and economic security unresolved.
For procurement and supply-chain executives, that combination makes tariff exposure increasingly difficult to treat as a temporary disruption scenario, since trade policy now sits alongside freight costs, commodity prices, exchange rates and supplier risk as a recurring input into commercial planning.
Manufacturers may respond by expanding regional sourcing, negotiating more flexible supplier agreements, reviewing customs classifications, reassessing inventory policies and building tariff scenarios into capital-allocation decisions, particularly where exposure to cross-border costs is large enough to influence investment returns.
Those responses do not require companies to assume that tariffs will continue to rise indefinitely, but they do reflect the commercial cost of operating without confidence about where rates, exemptions and rules of origin will settle over the longer term.
The immediate question for manufacturers is whether Washington and Ottawa can convert the current negotiations into a final agreement that delivers meaningful tariff relief, while the more consequential strategic issue is how much cross-border friction companies should now assume when designing North American production networks, choosing suppliers and committing capital for the years ahead.
Source:
The Wall Street Journal